Essential-Service NNN Real Estate Fund

Monthly Checks.
Real Assets.
Boring on Purpose.

A $40M fund acquiring long-term triple net leased buildings in early education, automotive services, and other recession- resistant retail, built on the same operating system that scaled Health Wealth Capital to $100M+ AUM.
Invest Now
Essential-Service NNN Real Estate Fund

Monthly Checks.
Real Assets
Boring on Purpose.

A $40M fund acquiring long-term triple net leased buildings in early education, automotive services, and other recession- resistant retail — built on the same operating system that scaled Health Wealth Capital to $100M+ AUM.
Invest Now
The Fund at a Glance

A proven playbook applied
to a new vertical.

100+%

DEPRECIATION BENEFIT

16–20%

Targeted IRR

8%

Annual Cash-on-Cash

5 yrs

Target Hold Period
The Fund at a Glance

A proven playbook applied to a new vertical.

100+%

DEPRECIATION BENEFIT

16–20%

Targeted IRR

8%

Annual Cash-on-Cash

5 yrs

Target Hold Period

Proven System. New Vertical.

Don’t have to take our word for it. See the playbook in real time at Health Wealth Capital.

Net Alliance Partners is run by the same team that built Health Wealth Capital — a $100M+ AUM medical NNN fund with 67 properties under management and an 18% average IRR across the portfolio. Four closed series. Distributions paid like clockwork.

Net Alliance applies that same operating system to a different vertical: non- medical essential-service retail. Early education. Automotive services. Gas stations. Car washes. Businesses Amazon will never replace.

Visit HealthWealth.Capital →
Health Wealth Capital — Live Track Record.
  • $100M+ Assets Under Management
  • 67 Properties Acquired
  • ~18% IRR Average Across Portfolio
  • 100+ Triple-Net Leases Negotiated
  • Distributions Paid Monthly Since Inception
Proven System. New Vertical.

You don’t have to take our word for it. Watch the playbook in real time at Health Wealth Capital.

Net Alliance Partners is run by the same team that built Health Wealth Capital — a $100M+ AUM medical NNN fund with 67 properties under management and an 18% average IRR across the portfolio. Eight years. Three closed series. Distributions paid like clockwork.

Net Alliance applies that same operating system to a different vertical: non- medical essential-service retail. Early education. Automotive services. Gas stations. Car washes. Businesses Amazon will never replace.

Visit HealthWealth.Capital →

Health Wealth Capital — Live Track Record.

  • $100M+ Assets Under Management
  • 67 Properties Acquired
  • ~18% IRR Average Across Portfolio
  • 100+ Triple-Net Leases Negotiated
  • Distributions Paid Monthly Since Inception
What We’ve Built Before

Two billion in combined assets.
Ten thousand doors.

$2B

Combined Assets

10000+

Doors Operated

100+

NNN Leases Closed

$200M+

Capital Raised

What We’ve Built Before

Two billion in combined assets.
Ten thousand doors.

$2B

Combined Assets

10000+

Doors Operated

100+

NNN Leases Closed

$200M+

Capital Raised

Why This, Why Now

Three structural advantages other real
estate categories can’t match.

We invest in the boring middle of the economy, daily-needs businesses that require physical space, generate predictable cash flow, and hand operating expenses to the tenant under long-term leases.

Structural Demand

Amazon-Proof

Daycares, gas stations, car washes, automotive services. None of these are getting disrupted by a website. Demand is structural — driven by daily routines, not consumer trends. When the economy softens, these businesses keep operating.

Lease Structure

Triple-Net Structure

Tenants pay rent plus taxes, insurance, and maintenance. The landlord owns the asset and collects the check. Long-term leases (10–20 years) with annual escalators built in. Predictable cash flow, minimal operating exposure.

Exit Strategy

REIT Arbitrage

We acquire individual properties at 7.5–9% cap rates. We assemble them into a stabilized portfolio. Public retail REITs trade at implied cap rates near 5.6%. That spread is the fund’s exit math — and it’s how the upside scenario gets to 25– 35% IRR.

Why This, Why Now

Three structural advantages other real estate categories can’t match.

We invest in the boring middle of the economy — daily-needs businesses that require physical space, generate predictable cash flow, and hand operating expenses to the tenant under long-term leases.

Structural Demand

Amazon-Proof

Daycares, gas stations, car washes, automotive services. None of these are getting disrupted by a website. Demand is structural — driven by daily routines, not consumer trends. When the economy softens, these businesses keep operating.

Lease Structure

Triple-Net Structure

Tenants pay rent plus taxes, insurance, and maintenance. The landlord owns the asset and collects the check. Long-term leases (10–20 years) with annual escalators built in. Predictable cash flow, minimal operating exposure.

Exit Strategy

REIT Arbitrage

We acquire individual properties at 7.5–9% cap rates. We assemble them into a stabilized portfolio. Public retail REITs trade at implied cap rates near 5.6%. That spread is the fund’s exit math — and it’s how the upside scenario gets to 25– 35% IRR.

The Process

Boring math, run with discipline.

01

Screen

~10 deals per week run through a proprietary auto-scoring model across 30+ data points: traffic counts, demographics, tenant credit, lease structure, market dynamics, going-in cap rate.

02

Underwrite

2–3 deals per week get full underwriting. Custom valuation model. Stress-tested cap rates, exit assumptions, and downside scenarios. Property condition reports ordered.

03

LOI

1–2 letters of intent per week submitted on deals that pass. Industry-leading LOI structures by a team that has closed 100+ triple-net leases.

04

Close

Tenant diligence runs in parallel with property diligence. Each closing is sequenced into a tranche. First money in, first money out — distributions begin within 90 days of close.

Investment Criteria

High Traffic, High Visibility Locations

High average daily traffic count (AADT). Preference for interstate or primary retail corridors.

Strong, Creditworthy Tenants

Multi-site operators with proven financials. Corporate or personal guarantees. Rent-to-revenue ratio under 10%.

Long-Term, Triple-Net Leases

10–20 year terms with 2%+ annual escalators. Tenant pays taxes, insurance, and
maintenance. Preference for absolute NNN.

Favorable Market Demographics

Population growth or stability over 5-year window. 50,000+ population within 10-mile
radius preferred.

Targeted Financial Performance

7.5–9% acquisition cap rate. 8%+ projected cash-on-cash. Built-in cap rate spread for REIT exit.

The Process

Boring math,
run with discipline.

“You have to have the right tenant and the right math. Other than that, it’s an incredibly stable investment.” — Tyson Cobb, on a recent investor webinar.

01

Screen

~10 deals per week run through a proprietary auto-scoring model across 30+ data points: traffic counts, demographics, tenant credit, lease structure, market dynamics, going-in cap rate.

02

Underwrite

2–3 deals per week get full underwriting. Custom valuation model. Stress-tested cap rates, exit assumptions, and downside scenarios. Property condition reports ordered.

03

LOI

1–2 letters of intent per week submitted on deals that pass. Industry-leading LOI structures by a team that has closed 100+ triple-net leases.

04

Close

Tenant diligence runs in parallel with property diligence. Each closing is sequenced into a tranche. First money in, first money out — distributions begin within 90 days of close.

Investment Criteria

HIGH TRAFFIC, HIGH VISIBILITY LOCATIONS

High average daily traffic count (AADT). Preference for interstate or primary retail corridors.

Strong, Creditworthy Tenants

Multi-site operators with proven financials. Corporate or personal guarantees. Rent-to-revenue ratio under 10%.

Long-Term, Triple-Net Leases

10–20 year terms with 2%+ annual escalators. Tenant pays taxes, insurance, and
maintenance. Preference for absolute NNN.

Favorable Market Demographics

Population growth or stability over 5-year window. 50,000+ population within 10-mile
radius preferred.

Targeted Financial Performances

7.5–9% acquisition cap rate. 8%+ projected cash-on-cash. Built-in cap rate spread for REIT exit.

Current Offering

$40M fund. ~35–45 properties.

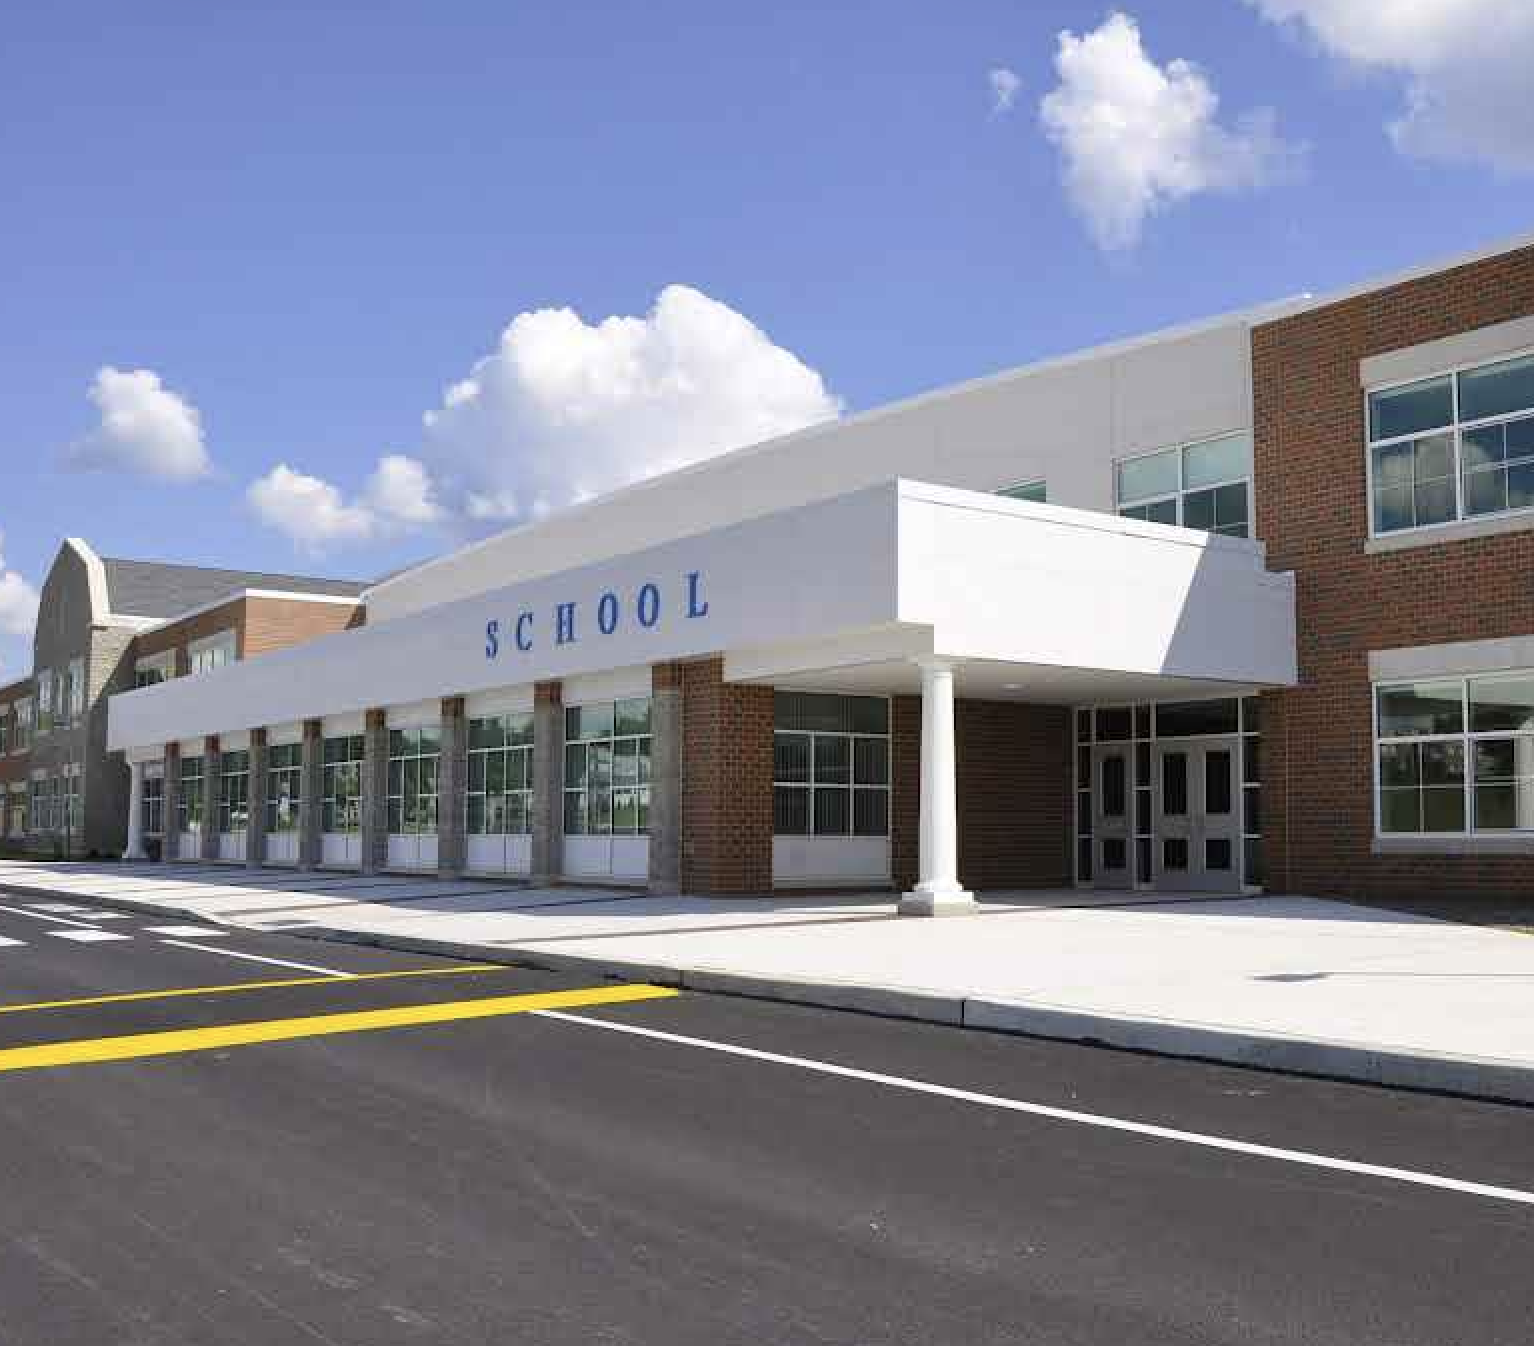
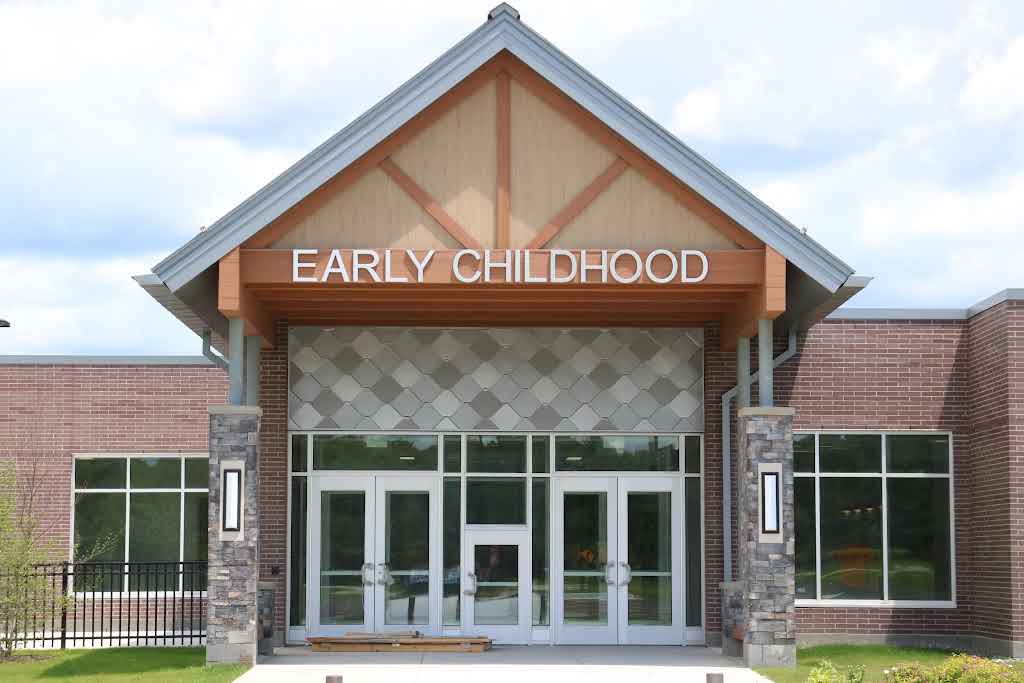
The fund opened with early education as the lead vertical. Three Eventus sites under PSA, two under LOI, with additional pipeline across gas stations, automotive, and other essential-service categories. Closings sequenced in tranches — first money in, first money out.

Fund Terms

Fund Size

$40M

Target Properties

~35–45 essential-service NNN buildings

Minimum Investment

$100,000 (Class A-1) / $500,000 (Class A-2)

Preferred Return

8% (Class A-1) / 9% (Class A-2)

Targeted Base IRR

16–20% (A-1) / 18–22% (A-2)

Targeted Upside IRR

25–35% (A-1) / 27–39% (A-2) — REIT/UPREIT exit

Equity Multiple

2.0–2.8x (A-1) / 2.2–3.0x (A-2)

Cash-on-Cash

8% paid monthly, beginning ~90 days post-
close

Hold Period

5 years (potential exit at 3)

Depreciation Benefit

Estimated +100% of invested capital

Profit Split (A-1)

80/20 to 15% IRR, 70/30 to 22%, 50/50 thereafter

Profit Split (A-2)

90/10 to 15% IRR, 85/15 to 22%, 75/25 thereafter

Loan-to-Value

70% (anticipated)

Debt Terms

5–7 yr fixed, 6.1–6.25% rate, 25–30 yr am, no prepay

Lead Tenant: Eventus Education

Eventus Education is a national school management company specializing in preschool acquisition, operational stabilization, and exit strategy. Founded by Dr. Jason Loy — 20 years in education leadership, repeated success scaling school platforms to acquisition by national operators including KinderCare.

Why Early Education Leads This Fund:
  • Essential demand — parents need daily child care to work
  • Limited supply — licensing takes 6–12 months per location
  • Government support — $50B+ in federal child care funding projected for 2026
  • Sticky customer base — families enroll for years, not months
  • Over half of U.S. households live in a ‘child care desert’
Sites Under Contract:

4510 Lawrenceville Rd, Loganville, GA — 15-yr absolute NNN, 8.15% cap
5301 Ricker Rd, Jacksonville, FL — 15-yr absolute NNN, 8.15% cap
Milwaukee, WI — Eventus Education (under PSA)

Current Offering

$40M fund. ~35–45 properties.
Lead asset: Eventus Education.

The fund opened with early education as the lead vertical. Three Eventus sites under PSA, two under LOI, with additional pipeline across gas stations, automotive, and other essential-service categories. Closings sequenced in tranches — first money in, first money out.

Fund Terms

Fund Size

$40M

Target
Properties

~35–45 essential-service NNN buildings

Minimum Investment

$100,000 (Class A-1) / $500,000 (Class A-2)

Preferred
Return

8% (Class A-1) / 9% (Class A-2)

Targeted
Base IRR

16–20% (A-1) / 18–22% (A-2)

Targeted
Upside IRR

25–35% (A-1) / 27–39% (A-2) — REIT/UPREIT exit

Equity
Multiple

2.0–2.8x (A-1) / 2.2–3.0x (A-2)

Cash-on-Cash

8% paid monthly, beginning ~90 days post-close

Hold Period

5 years (potential exit at 3)

Depreciation Benefit

Estimated +100% of invested capital

Profit Split (A-1)

80/20 to 15% IRR, 70/30 to 22%, 50/50 thereafter

Profit Split (A-2)

90/10 to 15% IRR, 85/15 to 22%, 75/25 thereafter

Loan-to-Value

70% (anticipated)

Debt Terms

5–7 yr fixed, 6.1–6.25% rate, 25–30 yr am, no prepay

Lead Tenant: Eventus Education

Eventus Education is a national school management company specializing in preschool acquisition, operational stabilization, and exit strategy. Founded by Dr. Jason Loy — 20 years in education leadership, repeated success scaling school platforms to acquisition by national operators including KinderCare.

Why Early Education Leads This Fund:

  • Essential demand — parents need daily child care to work
  • Limited supply — licensing takes 6–12 months per location
  • Government support — $50B+ in federal child care funding projected for 2026
  • Sticky customer base — families enroll for years, not months
  • Over half of U.S. households live in a ‘child care desert’

Sites Under Contract:

4510 Lawrenceville Rd, Loganville, GA — 15-yr absolute NNN, 8.15% cap
5301 Ricker Rd, Jacksonville, FL — 15-yr absolute NNN, 8.15% cap
Milwaukee, WI — Eventus Education (under PSA)

Asset Categories

Essential-service verticals we acquire in

Asset Categories

Essential-service verticals we acquire in

The People Behind the Fund

A team that has built this once in healthcare, now in essential-service retail.

Founder, Health Wealth Capital · Founder, Peak
Dental Services

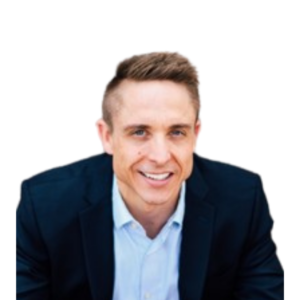
A.J. has spent nearly two decades inside the triple-net lease structure — first as a tenant operator, then as a landlord. He founded Peak Dental Services, scaled it to ~$100M in revenue and 50+ locations, and exited via majority sale to private equity in 2020. He then founded Health Wealth Capital, acquiring 67 medical NNN properties and delivering an estimated 18% average IRR.

MBA, Kellogg. BA, Carnegie Mellon. Former McKinsey &
Merrill Lynch.

Founder, Timberview Capital · Orthopedic
Surgeon

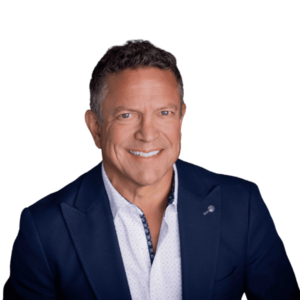
Tyson founded Timberview Capital, an investor network that deployed $36M across syndicated real estate in a single year. He has invested in triple-net leases since 2019, holding through COVID and the subsequent rate-hike cycle. He brings a clinician’s discipline to underwriting and a network of accredited investors actively allocating into NNN.

Chief Investment Officer, HWC · Founder, Adapt
Agency

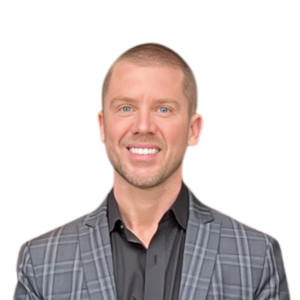
Derek leads capital strategy and investor relations across both ecosystems, as well as others.  He founded Adapt Agency, which has built capital-raising systems for 800+ companies touching $35B+ AUM. He has personally raised $100M+ for real estate offerings.

Operating CEO, Net Alliance Partners

Carter runs day-to-day execution — deal sourcing, underwriting, LOI submission, tenant diligence, and closing. A mechanical engineer by training, he applies an engineer’s discipline to the auto-scoring model, the LOI pipeline, and the close-management system — and invests personal capital in every deal.

Joe A. Romberg
Principal, Lutkins & Annis — Healthcare transactions & real estate

Trinity Bradley-Anderson
Tax Partner, Stockman Kast Ryan &
Company

Weekly Accounting
Full-service accounting & bookkeeping

The People Behind the Fund

A team that has already built this — once in healthcare, now in essential-service retail.

Founder, Health Wealth Capital · Founder, Peak
Dental Services

A.J. has spent nearly two decades inside the triple-net lease structure — first as a tenant operator, then as a landlord. He founded Peak Dental Services, scaled it to ~$100M in revenue and 50+ locations, and exited via majority sale to private equity in 2020. He then founded Health Wealth Capital, acquiring 67 medical NNN properties and delivering an estimated 18% average IRR.

MBA, Kellogg. BA, Carnegie Mellon. Former McKinsey &
Merrill Lynch.

Founder, Timberview Capital · Orthopedic
Surgeon

Tyson founded Timberview Capital, an investor network that deployed $36M across syndicated real estate in a single year. He has invested in triple-net leases since 2019, holding through COVID and the subsequent rate-hike cycle. He brings a clinician’s discipline to underwriting and a network of accredited investors actively allocating into NNN.

Chief Investment Officer, HWC · Founder, Adapt
Agency

Derek leads capital strategy and investor relations across both ecosystems, as well as others.  He founded Adapt Agency, which has built capital-raising systems for 800+ companies touching $35B+ AUM. He has personally raised $100M+ for real estate offerings.

Operating CEO, Net Alliance Partners

Carter runs day-to-day execution — deal sourcing, underwriting, LOI submission, tenant diligence, and closing. A mechanical engineer by training, he applies an engineer’s discipline to the auto-scoring model, the LOI pipeline, and the close-management system — and invests personal capital in every deal.

Joe A. Romberg
Principal, Lutkins & Annis — Healthcare transactions & real estate

Trinity Bradley-Anderson
Tax Partner, Stockman Kast Ryan &
Company

Weekly Accounting
Full-service accounting & bookkeeping

Frequently Asked Questions

Everything you need to know.

Same operating system. Different vertical. Health Wealth Capital acquires medical NNN buildings — dental practices, veterinary clinics, urgent care, plastic surgery. Net Alliance acquires non-medical essential-service NNN — early education, gas stations, car washes, automotive services. The underwriting model, the team, the tenant diligence approach, and the REIT exit strategy are identical. The asset class is different.

Three reasons. First, the deal flow is best — we have three Eventus sites under PSA, two more under LOI, and a tenant operator with a proven exit history. Second, the demand is structural — over half of U.S. households live in a child care desert, and federal funding is projected at $50B+ for 2026. Third, the lease structure is favorable — 15-year absolute NNN with 2% annual escalators at an 8.15% going-in cap.

Two paths. Base case: assemble a stabilized portfolio and sell properties individually at compressed cap rates of 6.5–7.5%, generating a 16–20% IRR. Upside case: scale the portfolio to $10M+ in NOI and merge with a public retail REIT trading at implied cap rates near 5.6%, generating a 25–35% IRR.

Monthly. Distributions begin approximately 90 days after a property closes. The fund closes in tranches — first money in, first money out. Your preferred return begins accruing on the day you fund. Targeted distribution rate is 8% annual cash-on-cash.

$100,000 for Class A-1 (8% preferred return). $500,000 for Class A-2 (9% preferred return, more favorable profit splits, larger Year 1 depreciation). All investments are private placements under SEC Regulation D, Rule 506(c).

Accredited investors only, per SEC Rule 506(c). Investors must meet income or net worth thresholds and provide third-party verification. The fund is open to U.S. investors only.

Year 1 depreciation is estimated at 50–70% for Class A-1 and 70–100% for Class A-2. Gas stations and certain education and automotive properties qualify for accelerated depreciation without a full cost segregation study. Investors should consult their tax advisors.

Three structural protections: (1) preferred return — investors receive 100% of cash flow to the pref rate before the sponsor receives anything; (2) conservative leverage — 70% LTV with 25–30 year amortization and fixed-rate debt; (3) tenant diligence — every tenant is underwritten on financials, multi-site presence, corporate guarantees, and rent-to-revenue ratio.

How to invest

Four steps from interested to funded.

01

Indicate Interest
5 min

Submit your investment interest through the CashFlow Portal. No documents signed, no capital committed. This step holds your spot in the next closing tranche. 

02

Schedule a Call
30 min

Thirty minutes with a principal — typically Carter or A.J. Walk through the offering, ask anything, decide if it’s a fit. No pressure to proceed.

03

Sign Documents
~4 weeks

Subscription documents, accreditation verification (via Parallel Markets), and standard private placement paperwork — completed inside the CashFlow Portal.

04

Fund Commitment
~10 weeks

Wire funds within 45 days of signing. Your capital deploys into the next acquisition cycle. Distributions begin approximately 90 days after the next property closes.

Get Started →
The investment process

Four steps from interested to funded.

01

Indicate Interest
5 min

Submit your investment interest through the CashFlow Portal. No documents signed, no capital committed. This step holds your spot in the next closing tranche. 

02

Schedule a Call
30 min

Thirty minutes with a principal — typically Carter or A.J. Walk through the offering, ask anything, decide if it’s a fit. No pressure to proceed.

03

Sign Documents
~4 weeks

Subscription documents, accreditation verification (via Parallel Markets), and standard private placement paperwork — completed inside the CashFlow Portal.

04

Fund Commitment
~10 weeks

Wire funds within 45 days of signing. Your capital deploys into the next acquisition cycle. Distributions begin approximately 90 days after the next property closes.

Net Alliance Partners

The right tenant.
The right math.
The rest is patience.

Same machine. New vertical. Open now.

Net Alliance Partners

The right tenant.
The right math.
The rest is patience.

Same machine. New vertical. Open now.